Small Loans Australia Home Loan Repayment Calculator
Calculate home loan repayments with our Home Loan Repayment Calculator. View detailed amortization charts, compare loan terms, and plan your mortgage with confidence.
Calculator results are estimates only and not quotes. Actual quotes will be provided by licensed brokers after you submit an enquiry.
Home Loan Details:
Important!
Home Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.). To find out if you qualify ... and for a free, personalised interest rate and repayment quote,
please CLICK HERE
Home Loan Amortisation Calculator
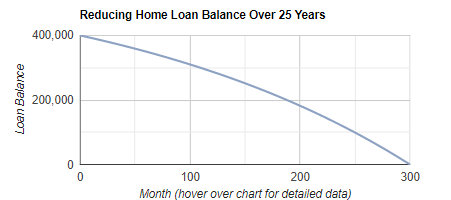
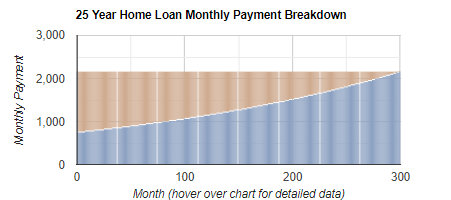
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Home Loan Repayment Calculator
Our Home Loan Repayment Calculator helps you estimate your mortgage repayments in Australia and understand how a loan may reduce over time. It is useful for budgeting, comparing loan terms, and visualising an amortisation schedule (how each repayment is split between interest and principal). The calculator is designed for planning only and works best when you enter realistic assumptions.
Important information: Results are estimates only and do not constitute a quote. Interest rates and loan features vary by lender and may change. This information is general and does not take into account your objectives, financial situation or needs. Consider whether it is appropriate for you and seek professional advice if required.
How to complete the calculator fields (in order):
1. Purchase Price: Enter the property purchase price. If you expect to borrow extra for costs, you may choose to include amounts such as stamp duty, insurance, and other buying costs in this figure so your estimate reflects your likely loan size. Enter whole numbers only (no dots or commas).
2. Deposit or Equity Value: Enter your cash deposit or usable equity from another property (if applicable). A higher deposit generally reduces the loan amount and can lower repayments. Enter whole numbers only (no dots or commas).
3. Term of Loan (years): Select the number of years to repay the loan. Longer terms usually reduce repayments but increase total interest paid over the life of the loan.
4. Interest Rate (% per annum): Select an interest rate for the simulation. Use a realistic rate and consider testing higher rates to understand “rate rise” risk.
5. Calculate: Click calculate to generate your results.
How to interpret the results:
1. Repayment estimate: Use this as a starting point for affordability checks, remembering real loans may include fees and different features.
2. Amortisation charts: Review the loan balance chart to see how your balance falls over time, and the interest versus principal chart to understand how early repayments are typically interest-heavy, then shift toward principal reduction later.
3. Compare scenarios: Adjust the term, deposit/equity, or interest rate and recalculate to compare loan terms and see how changes affect repayments and total interest over time.
Bad credit can make borrowing more challenging, but it does not automatically rule out every personal loan option. This guide explains how Australian borrowers can prepare for a small personal loan application, what lenders may look at beyond a credit score, and the risks to compare before applying. - read more
Secured and unsecured loans are two common ways Australians access personal finance. The main difference is whether the loan is backed by an asset, but that difference can affect interest rates, borrowing limits, repayment terms, eligibility and risk. - read more
Small business loans under $10,000 can help Australian sole traders, contractors, self-employed workers and small business owners manage cash flow, equipment, stock or short-term operating needs. Before applying, it is important to understand how lenders assess business income, repayments, security, documentation and affordability. - read more
Small and short-term loans in Australia are subject to important rules covering fees, suitability checks, disclosure, hardship and complaints. This guide explains the key borrower protections to understand before applying. - read more
Smart budgeting is the cornerstone of financial health. It helps you understand where your money is going and empowers you to make informed financial decisions. In Australia, like everywhere else, a well-managed budget can significantly improve your quality of life and financial stability. - read more
Personal loans can help with urgent expenses, debt consolidation or planned purchases, but they can also become costly if you borrow more than you need, overlook fees or enter an agreement without a repayment plan. This guide explains common personal loan mistakes and practical ways to assess, compare and manage borrowing decisions. - read more
Small loans under $10,000 can help Australian borrowers cover personal expenses or business needs, but their costs, terms and eligibility criteria vary. This guide explains how they usually work, what lenders may consider and what to compare before borrowing. - read more
It is no secret that the foundation of financial well-being is rooted in effective budgeting. In today's fast-paced world, where consumerism reigns, understanding how to manage one's finances has never been more crucial. Budgeting is not merely about restraining spending; it’s about creating a strategic plan that aligns with your financial goals and lifestyle. It allows individuals to gain control over their money, rather than letting their spending habits dictate their life course. - read more
Budgeting is not about removing every enjoyable expense from your life. At its best, a budget gives you a clear view of your income, spending, savings and debt so you can make calmer, more informed financial decisions. A practical financial plan can help you prioritise essentials, prepare for unexpected costs and make steady progress towards short-term and long-term goals. - read more
A fresh round of financial complaints reporting has put credit products back under the spotlight, with borrowers continuing to raise concerns about repayment pressure, fees, credit reporting, hardship support and the way lenders communicate when things go wrong. For Australians considering small loans, the message is practical rather than alarming: quick access to finance can be useful, but it should come with clear terms, realistic repayments and a plan if your income changes. - read more
Recent consumer finance reporting has again highlighted a problem many Australians already feel in their weekly budget: savings buffers are thin, and unexpected costs are arriving faster than wages can absorb them. Car repairs, medical bills, rent gaps, utility catch-ups and small business cash flow shortages can all turn into urgent funding decisions, especially for casual workers, sole traders and households with irregular income. - read more
Recent finance market reporting points to a sharper divide in Australia’s personal loan market: borrowers with stronger credit profiles and stable incomes may still find competitive offers, while applicants with patchier credit, casual income or heavier existing commitments can face higher pricing, tighter limits or more conditions. For Australians considering small loans, that gap matters more than the headline rate. - read more
Buy now pay later has shifted from a simple checkout convenience to a more formal part of Australia’s consumer credit landscape. Since the newer regulatory framework began applying, providers have faced clearer expectations around licensing, suitability checks, complaints handling and support for customers who fall behind. For everyday borrowers, this matters because BNPL, small personal loans and other short-term finance products often compete for the same household budget. - read more
Australia’s latest interest rate pause gives borrowers a little breathing space, but it should not be mistaken for a drop in loan costs. After months of pressure from inflation, rents, insurance, groceries and utilities, the Reserve Bank’s decision to keep the cash rate steady leaves many households and small business owners still managing repayments shaped by earlier increases. - read more
Australians searching for quick finance are being urged to slow down before responding to online loan offers, as scam activity continues to target people under cost-of-living pressure. The warning is especially relevant for borrowers who need urgent money for bills, car repairs, medical costs, rent gaps or short-term business cash flow. - read more
Australia’s credit regulator has kept the spotlight on how lenders respond when borrowers fall into financial hardship, a theme that matters directly to households and small business operators using small loans to manage short-term pressure. The message is simple: hardship support should be accessible, practical and clearly explained, not buried behind confusing processes or repeated requests for the same information. - read more
Australia’s corporate regulator has renewed attention on private credit, warning that a fast-growing part of the lending market is now facing a tougher test. Private credit generally refers to loans arranged outside the traditional banking system, often through funds, investment managers or specialist lenders. While this may sound distant from everyday small loans, the health of non-bank credit can still influence how finance is priced, assessed and made available. - read more
ASIC’s latest review of the motor vehicle finance sector is a timely reminder that the true cost of borrowing can sit well beyond the advertised interest rate. While the review focused on car loans, the lessons apply to many Australians considering small personal loans, short term finance or any borrowing arranged through a third party. - read more