Small Loans Australia Vehicle Lease Repayment Calculator
Use this calculator to calculate the monthly lease payments for a motor vehicle. Compare various car leasing interest rates, loan terms and residual/balloon payments.
Calculator results are estimates based on the inputs and assumptions used and are for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual costs and repayments may differ.
Car Lease Details:
Important!
Car Lease Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Car Lease Amortisation Calculator
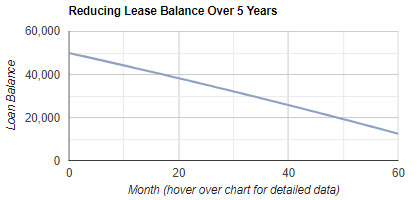
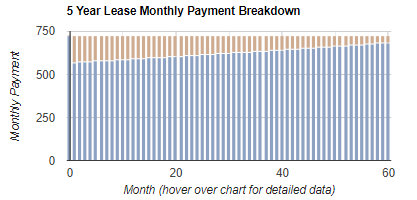
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Vehicle Lease Repayment Calculator
Our Vehicle Lease Repayment Calculator helps you estimate monthly lease repayments for a motor vehicle by modelling three key variables: interest rate, lease term, and the residual or balloon amount payable at the end. It’s important because small changes to any of these inputs can materially affect cash flow, total interest over the term, and the end-of-lease obligation, helping you compare scenarios before you speak with a lender or novated leasing provider.
How to complete the form for the best result:
1. Purchase Price
Enter the total amount you want financed for the vehicle. Include relevant upfront costs you intend to roll into the lease (for example, on-road costs or insurance where applicable). Use whole numbers only (no decimals, commas, or dots).
2. Balloon or Residual Value (percent of purchase price)
Select the residual percentage. A higher residual generally reduces the monthly payment but increases the amount left owing at the end, which can increase overall cost across the term. Choose a residual that matches your intended end-of-lease plan (keep, refinance, or sell).
3. Term of Loan (years)
Choose the number of years. Longer terms usually reduce monthly repayments but can increase total interest paid. Select a term that suits how long you expect to keep the vehicle and your budget tolerance.
4. Interest Rate (per annum)
Select an interest rate to simulate. Use a conservative rate when stress-testing affordability, because your actual rate may differ depending on lender policy and your circumstances.
5. Calculate
Click calculate to generate your estimated monthly lease repayment and amortisation visuals.
How to interpret the results:
1. Monthly repayment estimate: Use this as a budgeting guide and compare scenarios by adjusting term, rate, and residual.
2. Amortisation charts: Review how the balance reduces over time and how much of each payment is interest versus principal; this highlights when interest costs are highest and the impact of a larger residual.
ASIC compliance note: This guide is general information only and does not consider your objectives, financial situation or needs. Consider the full lease contract, fees, taxes, insurance, maintenance, and end-of-lease options before deciding, and consider getting personal advice if needed.
Loans can play a significant role in shaping our financial landscapes. For many Australians, they are vital tools for achieving milestones like buying a home, financing education, or starting a business. However, selecting the wrong type of loan can have a detrimental impact on your financial health, leaving you with unwanted debt and stress. - read more
Budgeting is not about removing every enjoyable expense from your life. At its best, a budget gives you a clear view of your income, spending, savings and debt so you can make calmer, more informed financial decisions. A practical financial plan can help you prioritise essentials, prepare for unexpected costs and make steady progress towards short-term and long-term goals. - read more
Small and short-term loans in Australia are subject to important rules covering fees, suitability checks, disclosure, hardship and complaints. This guide explains the key borrower protections to understand before applying. - read more
Debt can often feel like a formidable obstacle on the path to financial stability. Many individuals battle with various forms of debt, from high-interest credit cards to significant loans that seem to have an unyielding grip on their financial lives. Recognizing the challenges that debt presents is the critical first step towards regaining control of your personal finances. - read more
Budgeting is a foundational skill in the realm of personal finance, and as crucial as setting the sails is to a captain navigating through treacherous waters. Just as steady winds propel a ship towards its destination, a well-structured budget guides individuals towards their financial goals with confidence and control. - read more
Smart budgeting is one of the most vital tools in maintaining and improving your financial health. It provides a clear picture of your financial situation, helping you make informed decisions about spending, saving, and borrowing. - read more
Financial freedom starts with knowing where your money is going, what you owe and how you plan to reduce debt over time. These practical debt management tips can help Australians organise repayments, improve budgeting habits and make more informed decisions about borrowing and financial support. - read more
Interest rates play a vital role when it comes to borrowing money. They determine how much extra you'll pay on top of the amount you've borrowed. - read more
Secured and unsecured loans work in different ways. The main distinction is whether you provide an asset as collateral, but that difference can also affect interest rates, borrowing limits, approval steps and the risks you take on as a borrower. - read more
Recent consumer finance reporting has again highlighted a familiar pressure point for Australian households: managing several debts at once can become harder as everyday costs stay elevated. Credit cards, buy now pay later balances, car repairs, medical bills and overdue utilities can each look manageable in isolation, but together they may create a repayment calendar that is difficult to keep under control. - read more
A fresh round of financial complaints reporting has put credit products back under the spotlight, with borrowers continuing to raise concerns about repayment pressure, fees, credit reporting, hardship support and the way lenders communicate when things go wrong. For Australians considering small loans, the message is practical rather than alarming: quick access to finance can be useful, but it should come with clear terms, realistic repayments and a plan if your income changes. - read more
Recent consumer finance reporting has again highlighted a problem many Australians already feel in their weekly budget: savings buffers are thin, and unexpected costs are arriving faster than wages can absorb them. Car repairs, medical bills, rent gaps, utility catch-ups and small business cash flow shortages can all turn into urgent funding decisions, especially for casual workers, sole traders and households with irregular income. - read more
Recent finance market reporting points to a sharper divide in Australia’s personal loan market: borrowers with stronger credit profiles and stable incomes may still find competitive offers, while applicants with patchier credit, casual income or heavier existing commitments can face higher pricing, tighter limits or more conditions. For Australians considering small loans, that gap matters more than the headline rate. - read more
Buy now pay later has shifted from a simple checkout convenience to a more formal part of Australia’s consumer credit landscape. Since the newer regulatory framework began applying, providers have faced clearer expectations around licensing, suitability checks, complaints handling and support for customers who fall behind. For everyday borrowers, this matters because BNPL, small personal loans and other short-term finance products often compete for the same household budget. - read more
Australia’s latest interest rate pause gives borrowers a little breathing space, but it should not be mistaken for a drop in loan costs. After months of pressure from inflation, rents, insurance, groceries and utilities, the Reserve Bank’s decision to keep the cash rate steady leaves many households and small business owners still managing repayments shaped by earlier increases. - read more
Australians searching for quick finance are being urged to slow down before responding to online loan offers, as scam activity continues to target people under cost-of-living pressure. The warning is especially relevant for borrowers who need urgent money for bills, car repairs, medical costs, rent gaps or short-term business cash flow. - read more
Australia’s credit regulator has kept the spotlight on how lenders respond when borrowers fall into financial hardship, a theme that matters directly to households and small business operators using small loans to manage short-term pressure. The message is simple: hardship support should be accessible, practical and clearly explained, not buried behind confusing processes or repeated requests for the same information. - read more
Australia’s corporate regulator has renewed attention on private credit, warning that a fast-growing part of the lending market is now facing a tougher test. Private credit generally refers to loans arranged outside the traditional banking system, often through funds, investment managers or specialist lenders. While this may sound distant from everyday small loans, the health of non-bank credit can still influence how finance is priced, assessed and made available. - read more
All finance quotes are provided free (via our secure server) and without obligation. We
respect your
privacy.
Knowledgebase
Personal Loan: A personal loan is usually made by a financial institution to an individual person without the need for the provision of asset security. Personal loans can generally be obtained for any worthwhile purpose subject to the lending criteria of the financ