The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Secured and unsecured loans work in different ways. The main distinction is whether you provide an asset as collateral, but that difference can also affect interest rates, borrowing limits, approval steps and the risks you take on as a borrower.
Loans generally involve borrowing money from a lender and agreeing to repay it over time, usually with interest. They can be used for different purposes, such as buying a car, financing a home, covering a personal expense or consolidating debt.
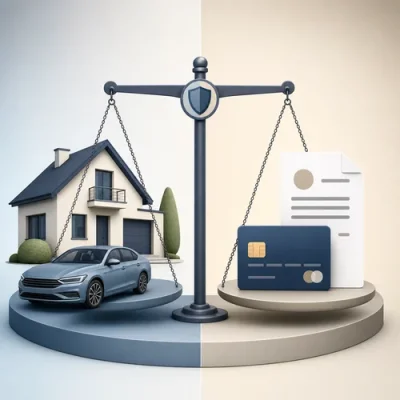
Most loans fall into two broad categories: secured and unsecured. A secured loan is backed by collateral, such as a car, home or another asset. An unsecured loan does not require collateral and is usually assessed mainly on the borrower’s creditworthiness and ability to repay.
Understanding the difference matters because the loan type can affect the cost of borrowing, how much you may be able to borrow, how quickly the loan may be assessed and what happens if repayments are not made.
Secured and unsecured loans at a glance
| Feature |
Secured loan |
Unsecured loan |
| Collateral |
Requires an asset to secure the loan. |
No asset is pledged as security. |
| Common examples |
Mortgages and car loans. |
Personal loans and credit cards. |
| Lender risk |
Lower for the lender because the asset can be used to recover losses if the borrower defaults. |
Higher for the lender because there is no specific asset to repossess. |
| Interest rates |
Often lower than unsecured loans because collateral reduces lender risk. |
Often higher because the lender has less security. |
| Borrowing limits |
May be higher where the lender accepts the value of the asset as security. |
May be lower because the loan is not backed by collateral. |
| Key borrower risk |
The secured asset may be repossessed or sold if repayments are not made. |
No pledged asset is at direct risk, but missed repayments can still have serious financial consequences. |
What is a secured loan?
A secured loan is a loan where the borrower provides an asset as collateral. The asset gives the lender a form of security. If the borrower does not meet the repayment terms, the lender may have the right to take or sell the asset to recover the amount owed.
Common examples include mortgages, where the property is used as security, and car loans, where the vehicle being purchased may be used as collateral. If you are considering vehicle finance, a car loan repayment calculator can help you estimate how different loan terms may affect repayments.
Because the lender has security over an asset, secured loans may come with lower interest rates or higher borrowing limits than comparable unsecured loans. However, this depends on the lender, the asset, the borrower’s circumstances and the loan terms.
Advantages of secured loans
- Potentially lower interest rates: Collateral can reduce the lender’s risk, which may be reflected in the interest rate offered.
- Potentially higher borrowing limits: A lender may be prepared to lend more when the loan is supported by an acceptable asset.
- Useful for major purchases: Secured loans are commonly used for larger purchases such as homes and cars.
Disadvantages of secured loans
- Risk to the asset: If repayments are not made, the borrower may lose the asset used as collateral.
- More checks may be involved: The lender may need to verify the asset and its value, which can make the approval process longer than some unsecured loan processes.
- Less suitable if you do not want to pledge property: Borrowers who do not have an acceptable asset, or who are not comfortable putting an asset at risk, may prefer to consider unsecured options.
What is an unsecured loan?
An unsecured loan does not require the borrower to provide collateral. Instead, the lender relies on factors such as creditworthiness and the borrower’s promise to repay.
Common examples include personal loans and credit cards. Credit cards allow borrowing up to an approved credit limit, with interest generally applying if the balance is not paid in full by the due date. Personal loans usually provide a lump sum that is repaid in instalments over an agreed period.
Because there is no pledged asset for the lender to recover if the borrower defaults, unsecured loans can carry higher interest rates and may have lower borrowing limits than secured loans. A strong credit history can influence the terms offered, although each lender applies its own assessment process.
Advantages of unsecured loans
- No collateral required: You do not need to pledge a car, home or other asset as security for the loan.
- No direct risk to a pledged asset: Because no asset is pledged, there is no specific collateral for the lender to repossess if repayments are missed.
- Potentially faster assessment: Without the need to value collateral, the process can involve fewer asset-related checks.
Disadvantages of unsecured loans
- Potentially higher interest rates: Lenders may charge more because they do not have security over an asset.
- Potentially lower borrowing limits: Some lenders may be less willing to lend larger amounts without collateral.
- Credit history can be important: Since the loan is not secured by an asset, creditworthiness can play a significant role in the lender’s assessment.
How to choose between a secured and unsecured loan
The right loan structure depends on the purpose of the borrowing, the amount needed, the borrower’s financial position and the level of risk they are willing to accept. The choice is not only about interest rates; it is also about what security is being offered and what obligations are created.
Consider the reason for borrowing
Secured loans are commonly used for larger purchases where the asset itself can act as collateral, such as a home or vehicle. Unsecured loans may be used for smaller or shorter-term personal needs where the borrower does not want to provide an asset as security. For more background on smaller borrowing needs, see this guide to how small loans under $10,000 work in Australia.
Think about collateral and risk tolerance
With a secured loan, the main risk is that the asset used as collateral may be repossessed or sold if repayments are not made. With an unsecured loan, there is no pledged asset at direct risk, but the borrower may face higher interest rates and stricter borrowing limits.
Borrowers should consider whether they are comfortable using an asset as security and whether they can manage the repayments under the proposed terms.
Compare rates, fees and repayment terms
Interest rates and repayment terms can differ significantly between loan types and lenders. Secured loans often have lower rates because the lender has collateral, while unsecured loans often have higher rates because the lender takes on more risk.
Before choosing a loan, compare the repayment amount, interest calculation method, fees, loan term and any conditions that apply. If you are estimating repayments on an unsecured personal loan, a personal loan repayment calculator can help illustrate how the loan amount, rate and term may affect repayments.
Tips for reviewing loan terms
Loan terms can have a lasting effect on your finances, so it is important to review the details carefully before signing any agreement.
- Check your credit position: A stronger credit history may help when seeking more favourable terms, particularly for unsecured loans.
- Compare offers from different lenders: Rates, fees and conditions can vary. If you are ready to compare loan options, you can start from the small loans quote start page.
- Read the fine print: Look for fees, repayment rules, interest calculation details and any conditions that could affect the total cost of the loan.
- Ask questions before signing: If any clause or cost is unclear, seek clarification before entering into the agreement.
- Consider professional guidance: Where the decision is complex, speaking with an appropriately qualified adviser or learning more about the role of finance brokers may help you understand the process.
Key takeaways
Secured and unsecured loans differ mainly in whether collateral is required. A secured loan uses an asset, such as a car or home, as security. This can reduce risk for the lender and may lead to lower interest rates or higher borrowing limits, but it also creates the risk of losing the asset if repayments are not made.
An unsecured loan does not require collateral. This can make it more flexible for borrowers who do not want to pledge property, but it may come with higher interest rates, lower borrowing limits or stricter assessment criteria.
Before deciding, consider why you need the loan, how much you need to borrow, whether you have collateral, how comfortable you are with the risks and whether the repayments fit your financial situation.
Published: Sunday, 4th May 2025
Author: Paige Estritori






No comments yet. Be the first to share your thoughts.