Small Loans Australia Personal Loan Repayment Calculator
Explore potential personal loan repayment scenarios with our Personal Loan Calculator. Test different borrowing amounts, interest rates and loan terms, and review estimated repayment schedules to see how varying assumptions may affect your repayments and total borrowing costs.
Calculator results are estimates based on the inputs and assumptions used and are for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual costs and repayments may differ.
Personal Loan Details:
Important!
Personal Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Personal Loan Amortisation Calculator
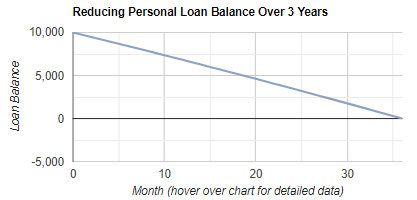
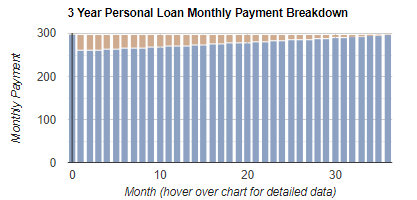
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Personal Loan Repayment Calculator
Our Personal Loan Repayment Calculator helps you estimate your ongoing loan repayments and the total cost of borrowing before you apply. By adjusting the loan amount, loan term and interest rate, you can compare scenarios and choose a repayment level that better fits your budget. It also provides an amortisation view so you can see how each repayment is split between interest and principal over time.
Important note for ASIC compliance: this calculator provides general information only and does not take into account your objectives, financial situation or needs. Results are estimates and may not include lender fees, comparison rates, commissions, insurance, redraw features, or changes to your interest rate. Always check a lender’s final quote and loan contract before deciding.
How to complete the form for the best result
1. Loan Amount Required: Enter the total amount you want to borrow in Australian dollars as a whole number (no decimals or commas). Use the amount you actually need, not the maximum you might be approved for, to avoid overpaying interest.
2. Term of Loan: Select the number of years you plan to repay the loan over. A longer term can reduce the monthly repayment, but typically increases the total interest paid over the life of the loan.
3. Interest Rate: Choose an annual interest rate for the simulation. If you have a lender quote, use that rate. If not, test a conservative range to understand best case and worst case outcomes.
4. Calculate: Click the calculate button to generate your results.
How to interpret the results
1. Repayment estimate: Treat the repayment figure as your baseline commitment. Stress-test your budget by increasing the rate or shortening the term to see if repayments remain affordable.
2. Amortisation and graphs: Review the month-by-month amortisation view and charts to understand how the balance reduces and how early repayments often include a higher interest portion, shifting toward more principal over time.
3. Compare scenarios: Re-run the calculator with different terms and rates to balance affordability (cash flow) against total interest (overall cost).
Budgeting is not about removing every enjoyable expense from your life. At its best, a budget gives you a clear view of your income, spending, savings and debt so you can make calmer, more informed financial decisions. A practical financial plan can help you prioritise essentials, prepare for unexpected costs and make steady progress towards short-term and long-term goals. - read more
Bad credit can make a personal loan application more difficult, but it does not always mean every option is closed. Understanding your credit position, repayment capacity, loan types and lender requirements can help you compare personal loan options more carefully and avoid taking on debt that may be difficult to manage. - read more
Small business loans under $10,000 can help Australian sole traders, contractors, self-employed workers and small business owners manage cash flow, equipment, stock or short-term operating needs. Before applying, it is important to understand how lenders assess business income, repayments, security, documentation and affordability. - read more
Your credit score can influence how lenders assess applications for loans, credit cards and other credit products. While there is no guaranteed instant fix, there are practical steps Australians can take to identify errors, reduce avoidable risks and build habits that support a healthier credit profile over time. - read more
Debt can often feel like a formidable obstacle on the path to financial stability. Many individuals battle with various forms of debt, from high-interest credit cards to significant loans that seem to have an unyielding grip on their financial lives. Recognizing the challenges that debt presents is the critical first step towards regaining control of your personal finances. - read more
Small loans under $10,000 can help Australian borrowers cover personal expenses or business needs, but their costs, terms and eligibility criteria vary. This guide explains how they usually work, what lenders may consider and what to compare before borrowing. - read more
Interest rates play a vital role when it comes to borrowing money. They determine how much extra you'll pay on top of the amount you've borrowed. - read more
Financial freedom starts with knowing where your money is going, what you owe and how you plan to reduce debt over time. These practical debt management tips can help Australians organise repayments, improve budgeting habits and make more informed decisions about borrowing and financial support. - read more
Your credit score and credit report can influence how lenders assess a personal loan application. If your credit history is less than ideal, there are practical steps you can take to better understand your position, correct errors, improve financial habits and prepare a stronger application over time. - read more
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85 per cent has sharpened the repayment question for Australians considering small personal or business borrowing. The increase took effect on 4 November, and major lenders have already begun moving rates across variable products, including home loans and some business and personal lending. - read more
Australia’s new card surcharge rules have turned a small checkout fee into a wider cash flow question for consumers and small businesses. Since 1 October 2026, businesses have generally been unable to add card payment surcharges for major card networks, making payments look simpler at the counter but leaving operators to decide how remaining merchant costs fit into their pricing, margins and budgeting. - read more
Recent consumer finance reporting has again highlighted a familiar pressure point for Australian households: managing several debts at once can become harder as everyday costs stay elevated. Credit cards, buy now pay later balances, car repairs, medical bills and overdue utilities can each look manageable in isolation, but together they may create a repayment calendar that is difficult to keep under control. - read more
A fresh round of financial complaints reporting has put credit products back under the spotlight, with borrowers continuing to raise concerns about repayment pressure, fees, credit reporting, hardship support and the way lenders communicate when things go wrong. For Australians considering small loans, the message is practical rather than alarming: quick access to finance can be useful, but it should come with clear terms, realistic repayments and a plan if your income changes. - read more
Recent consumer finance reporting has again highlighted a problem many Australians already feel in their weekly budget: savings buffers are thin, and unexpected costs are arriving faster than wages can absorb them. Car repairs, medical bills, rent gaps, utility catch-ups and small business cash flow shortages can all turn into urgent funding decisions, especially for casual workers, sole traders and households with irregular income. - read more
Recent finance market reporting points to a sharper divide in Australia’s personal loan market: borrowers with stronger credit profiles and stable incomes may still find competitive offers, while applicants with patchier credit, casual income or heavier existing commitments can face higher pricing, tighter limits or more conditions. For Australians considering small loans, that gap matters more than the headline rate. - read more
Buy now pay later has shifted from a simple checkout convenience to a more formal part of Australia’s consumer credit landscape. Since the newer regulatory framework began applying, providers have faced clearer expectations around licensing, suitability checks, complaints handling and support for customers who fall behind. For everyday borrowers, this matters because BNPL, small personal loans and other short-term finance products often compete for the same household budget. - read more
Australia’s latest interest rate pause gives borrowers a little breathing space, but it should not be mistaken for a drop in loan costs. After months of pressure from inflation, rents, insurance, groceries and utilities, the Reserve Bank’s decision to keep the cash rate steady leaves many households and small business owners still managing repayments shaped by earlier increases. - read more
Australians searching for quick finance are being urged to slow down before responding to online loan offers, as scam activity continues to target people under cost-of-living pressure. The warning is especially relevant for borrowers who need urgent money for bills, car repairs, medical costs, rent gaps or short-term business cash flow. - read more