The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
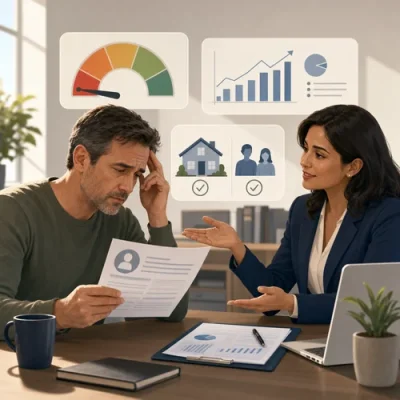
Bad credit can make a personal loan application more difficult, but it does not always mean every option is closed. Understanding your credit position, repayment capacity, loan types and lender requirements can help you compare personal loan options more carefully and avoid taking on debt that may be difficult to manage.
What does bad credit mean in Australia?
Your credit score is a numerical summary of your credit history and is one factor lenders may use when assessing whether you are likely to repay borrowed money. In Australia, credit scores commonly range from 0 to 1200, and scores below about 620 are often described as bad credit.
Your credit report can include information such as credit applications, repayment history and missed payments. Lenders may review this information alongside your income, expenses, employment stability and existing debts when considering a personal loan application.
Bad credit can make approval more difficult and may affect the interest rate, fees or loan conditions offered. However, it is not the only factor a lender may consider, and different lenders may assess applications in different ways.
Common misconceptions about bad credit personal loans
A common misconception is that a poor credit score automatically rules out any personal loan. In practice, some lenders consider applicants with imperfect credit histories, although the loan may cost more or come with stricter conditions.
Another misconception is that traditional banks are the only source of personal loans. Depending on the borrower's circumstances, options may also include online lenders, credit unions and peer-to-peer lending platforms. Some alternative lenders look beyond the credit score and may also assess income, employment history and broader financial circumstances.
That does not mean every bad credit loan is suitable or affordable. Higher perceived risk can lead to higher rates, additional fees or shorter repayment terms, so it is important to compare the full cost of the loan rather than focusing only on whether approval may be possible.
Assess your finances before applying
Before applying for a personal loan, it is useful to understand your credit position and your capacity to make repayments. This can help you avoid borrowing more than you can realistically afford.
Review your credit report
Obtain a copy of your credit report and check it carefully for errors, such as incorrect personal details or accounts that do not belong to you. If you find inaccurate information, you can dispute it with the credit reporting body. Correcting errors may improve how your credit position is viewed.
Check your income, expenses and existing debts
Create a realistic monthly budget that lists your income, fixed expenses and variable spending. Fixed expenses may include rent, utilities and groceries, while variable costs may include entertainment, eating out or other discretionary spending.
This process can show how much room you have for repayments after essential costs. You can also use a personal loan repayment calculator to estimate how different loan amounts, terms and rates may affect repayments.
Borrow only what you need
It can be tempting to apply for the highest amount available, but a larger loan can create extra pressure if your circumstances change. Consider the purpose of the loan, the repayment amount you can manage, and whether unexpected expenses could affect your ability to pay on time.
Ways to improve your credit position before applying
If the loan is not urgent, taking time to improve your credit position may strengthen a future application. Improvements are not immediate, but consistent financial behaviour can help build a more positive record over time.
- Pay bills and debts on time: A record of timely payments can help demonstrate financial responsibility.
- Reduce existing debt: Lowering outstanding balances may improve your overall financial position.
- Use a repayment strategy: Some borrowers focus on smaller debts first to build momentum, while others prioritise higher-interest debts first to reduce interest costs.
- Maintain a practical budget: A budget can help prevent overspending and free up money for debt reduction.
- Keep evidence of positive changes: Recent payslips, savings records and proof of regular payments may help show that your current circumstances are stronger than your past credit history suggests.
For more detail on credit improvement steps, you may want to read this guide on how to boost your credit score before applying.
Loan options if you have bad credit
Bad credit borrowers may encounter several types of personal loan products. Each has different risks, costs and eligibility considerations.
| Option |
How it works |
Key considerations |
| Secured personal loan |
The borrower provides an asset, such as a car, as collateral. |
May be more accessible or cheaper than an unsecured loan, but the asset may be at risk if repayments are not made. |
| Unsecured personal loan |
No collateral is required. |
May be harder to obtain with bad credit and may have higher rates because the lender has less security. |
| Online or alternative lender loan |
Some lenders assess income, employment and overall financial circumstances as well as credit history. |
Terms vary widely, so it is important to compare fees, rates and repayment obligations carefully. |
| Peer-to-peer loan |
Funding may come from individual investors through a lending platform. |
Assessment criteria and pricing can differ from traditional lenders. |
| Payday or short-term high-cost loan |
Designed for short-term borrowing and often due quickly. |
Can be expensive and may increase the risk of debt stress if not repaid on time. |
If you are weighing up collateral and repayment risk, this guide to secured and unsecured loans explains the differences in more detail.
How to compare bad credit personal loan offers
When comparing personal loan options, the lowest advertised interest rate is not always the full story. Loan term, repayment frequency, fees and penalties can all affect the total cost.
If you decide to compare personal loan options, review the details carefully and consider whether the repayments fit your budget before making an enquiry or application.
Compare more than the rate
- Interest rate and whether it is fixed or variable.
- Application, establishment or ongoing account fees.
- Late payment fees or default charges.
- Early repayment fees or restrictions.
- Loan term and total amount repayable over the life of the loan.
- Repayment frequency and whether it matches your income cycle.
Read the fine print
Before accepting a loan, read the lender's terms and conditions. Pay attention to fees, penalties and any conditions that could increase the cost of the loan. If any term is unclear, ask the lender to explain it before proceeding.
Be realistic about affordability
A loan may appear manageable at first, but a short term or high fees can increase repayment pressure. Compare the total repayment amount and make sure there is enough room in your budget for essential expenses and unexpected costs.
Tips for preparing a stronger application
A well-prepared application can help a lender assess your situation clearly. It does not guarantee approval, but it can reduce delays and ensure the information provided is consistent.
- Gather documents before applying: This may include identification, payslips, bank statements and details of current debts.
- Check that information is accurate: Make sure your application details match your supporting documents and credit report.
- Highlight current financial strengths: Stable employment, consistent income, regular savings or recent repayment improvements may help provide context.
- Be honest about credit history: Lenders are likely to review your credit report, so it is better to provide accurate information and explain any relevant circumstances if asked.
- Avoid multiple unnecessary applications: Submitting many applications in a short period may not help your position and can make your finances appear under pressure.
Using a co-signer or guarantor
Some borrowers consider applying with a co-signer or guarantor. This can provide additional security for the lender because another person agrees to take responsibility if the borrower cannot meet the repayment obligations.
This arrangement should be approached carefully. The co-signer or guarantor needs to understand the legal and financial responsibility involved, and the borrower should consider the potential impact on both the relationship and the other person's finances if repayments are missed.
Negotiating and asking questions
Some loan terms may be open to discussion, depending on the lender and the borrower's circumstances. If you have evidence of improved financial stability, such as steady income or a better recent repayment record, you may be able to ask whether more suitable terms are available.
Questions to ask may include:
- What is the total amount I will repay over the full loan term?
- Are there any upfront, monthly, late payment or early repayment fees?
- Can I make extra repayments?
- What happens if I miss a repayment?
- Will the loan be secured against an asset?
- Can the repayment date align with my pay cycle?
Even if the lender does not change the rate or terms, asking these questions can help you understand the commitment before you proceed.
When financial counselling may help
If debt feels difficult to manage, or if you are considering a loan mainly to cover existing repayments, financial counselling may be useful before taking on more credit. Financial counsellors can provide free, independent and confidential guidance.
A financial counsellor may help you understand your debts, prioritise repayments, communicate with creditors and consider options for improving your financial position. They may also help you understand loan terms and the risks of taking on additional debt while you are under financial pressure.
Seeking help early can make it easier to plan a way forward and avoid decisions that may worsen debt stress.
Key takeaways
- Bad credit can make personal loan approval harder and may affect rates, fees and loan conditions.
- Lenders may assess more than your credit score, including income, expenses, employment and existing debts.
- Check your credit report for errors and understand your budget before applying.
- Secured loans may be easier to access but put the secured asset at risk if repayments are missed.
- Compare the full cost of a loan, including fees and penalties, not just the advertised interest rate.
- Consider financial counselling if debt is becoming difficult to manage or you are unsure whether more borrowing is appropriate.
Published: Monday, 10th Jun 2024
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.